Temporary vs permanent disability in California workers’ compensation is a distinction that shapes everything about how a claim unfolds — when benefits start, when they end, how much they pay, and what happens to your case next. Many injured workers confuse the two, assume one automatically leads to the other, or miss the transition point that connects them. That confusion costs money: premature settlements, missed SDI bridges, and unchallenged disability ratings that undervalue lasting impairment. This guide explains each benefit type clearly, how they relate to each other, and what the 2026 rates and rules mean for your specific situation.
Temporary vs Permanent Disability California: The Core Distinction
The biggest difference between temporary and permanent disability is purpose. Temporary disability is about wage loss during recovery — it replaces income while you are unable to perform your regular job. Permanent disability is about lasting impairment after recovery — it compensates for physical loss that does not fully resolve even after treatment is complete. The two benefits serve different needs, are calculated differently, and operate on entirely separate timelines. Understanding this distinction prevents one of the most common and costly mistakes in California workers’ compensation: settling a case for permanent disability before the full extent of that permanent impairment is known.
According to the California Division of Workers’ Compensation, both temporary and permanent disability benefits are part of the wage replacement and impairment compensation framework established by the California Labor Code — but they are governed by different statutes, different rate schedules, and different eligibility rules. For a complete breakdown of all seven California workers’ compensation benefit categories and how they interact, see our post on what benefits you are entitled to after a workplace injury in California.
Temporary Disability — What It Is and When It Applies
Temporary disability benefits begin when a work injury prevents you from performing your regular job duties and a physician certifies that you are unable to work. California law requires the insurer to begin making payments within 14 days of receiving that medical certification. TTD benefits pay two-thirds of your gross average weekly wage — minimum $264.61 per week, maximum $1,764.11 per week for 2026 injuries — and continue on a biweekly schedule until you return to work, reach maximum medical improvement, or hit the statutory cap.
There are two forms of temporary disability. Temporary total disability applies when you cannot work in any capacity — not even modified or light duty. Temporary partial disability applies when you return to work in a restricted capacity but earn less than your pre-injury wage — TPD pays two-thirds of the wage difference between your pre-injury AWW and your current modified-duty earnings. Both are subject to the same 2026 rate floor and ceiling, and both are calculated from the same average weekly wage foundation.
The injury date locks in the applicable rate year — not the date payments begin or the date a settlement is reached. A worker injured on January 5, 2026 receives 2026 rates even if checks do not arrive until March. An insurer paying 2025 rates for a 2026 injury is underpaying, and the difference accumulates over every week of the claim. The automatic late payment penalty under Labor Code Section 4650 — 10% on any payment made more than 14 days after it is due — applies independently to each late or incorrect payment. For more on identifying and challenging underpayments, see our complete guide on how much workers’ comp pays in California.
The 104-Week Cap — and What Happens When TTD Runs Out
California Labor Code Section 4656 limits temporary total disability benefits to 104 weeks within five years of the date of injury for most work injuries — approximately two years of weekly payments. When the 104-week cap is reached, TTD payments stop regardless of whether the worker has returned to work or reached MMI. This is one of the most financially dangerous moments in a California workers’ comp claim: the checks stop, but the injury is still present, the medical picture may still be developing, and the permanent disability assessment may not yet be complete.
California recognizes an extended 240-week TTD cap for specific serious injuries including severe burns, certain amputations, hepatitis B or C, and other conditions listed under Labor Code Section 4656(c). Workers with these injuries can receive TTD for up to 240 weeks within five years of the injury date. If your injury qualifies for the extended cap and you were cut off at 104 weeks, that termination is a challengeable error worth raising immediately through the WCAB.
When 104 weeks of TTD are exhausted before MMI is reached, California’s State Disability Insurance program through the Employment Development Department may provide up to 52 additional weeks of partial wage replacement. SDI is funded by California payroll withholding — the SDI deduction on every paycheck — and operates completely separately from the workers’ compensation system. Transitioning from expiring TTD to SDI without a gap requires timely application, and the timing matters: applying after a gap has already opened is harder than filing in advance of the cutoff. For more on what to do when TTD stops unexpectedly, see our post on what to do when workers’ comp benefits stop in California.
Maximum Medical Improvement — The Pivot Point Between TD and PD
Maximum medical improvement is the single most important moment in the transition from temporary to permanent disability. MMI — also called “permanent and stationary” status in California workers’ compensation — is the point at which a treating physician determines that your condition has stabilized and further significant improvement is not expected with continued treatment. It is not the same as being fully recovered. It is a medical determination that the condition has reached its stable endpoint, whether or not that endpoint involves complete healing.
When MMI is reached, three things happen simultaneously: temporary disability payments end, the permanent and stationary report is prepared, and the permanent disability rating process begins. This transition is where the claim’s final value begins to take shape — and it is also where the most significant financial disputes occur. The P&S report is the medical document that converts your specific impairments into the data points that produce a disability rating, and the quality and completeness of that report directly affects the rating that results. An inadequate P&S report can produce a rating that substantially undervalues the functional impact of the injury.
Settling a workers’ compensation case before MMI is reached means settling before the full extent of permanent impairment is known. This is one of the most common ways injured workers leave significant compensation behind — accepting a number based on what the injury looks like during recovery rather than what it looks like at its stable endpoint. For more on why settlement timing matters so much, see our post on should I accept the insurance company’s first offer.
Permanent Disability — What It Is and How It Is Calculated
Permanent disability benefits compensate for the lasting physical impairment that remains after maximum medical improvement. Unlike temporary disability — which is tied to your inability to earn — permanent partial disability is paid based on the impairment itself, not on whether you are working. A worker who returns to full employment at the same wage can still receive scheduled PPD payments or settle for a lump sum representing those payments.
California uses the Permanent Disability Rating Schedule and the AMA Guides to convert the medical findings in the P&S report into a disability rating from 1% to 99% for partial disability cases. That rating determines the weekly benefit amount and total number of weeks of PPD payments. For injuries on or after January 1, 2014, the weekly PPD rate ranges from $160 to $290 depending on the rating percentage. The maximum weekly PPD rate of $290 applies to ratings of 70% and above. Total payments are calculated by multiplying the weekly rate by the number of weeks assigned to the rating under the statutory schedule.
A worker with a 10% permanent disability rating and a 2026 injury receives fewer weeks of PPD at a lower weekly rate than a worker with a 35% rating. The rating is not just a medical determination — it is the number that controls the total financial value of the permanent disability portion of the claim. For a full breakdown of how PPD rates, life pensions, and PTD interact, see our guide on how much workers’ comp pays in California.
The QME Process — When Ratings Are Disputed
The permanent disability rating process is the most frequently contested stage of a California workers’ compensation claim. When the treating physician’s rating and the insurer’s position differ — which is common, because the insurer’s financial interest lies in the lower number — the dispute goes to a Qualified Medical Evaluator. The QME is a physician appointed by the California Division of Workers’ Compensation to provide an independent medical opinion on disputed issues including permanent disability rating, causation, and apportionment.
In represented cases, the parties use a panel QME — a list of three physicians from which each side strikes one, leaving the third to conduct the evaluation. The QME’s report is typically given significant weight by the WCAB in resolving rating disputes. An attorney who understands how to prepare a client for a QME examination, what questions to raise with the QME, and how to challenge an inadequate QME report produces materially better rating outcomes than a self-represented claimant navigating the process alone. For more on what this process looks like in practice, see our post on what to expect from a workers’ compensation attorney in Orange County.
Apportionment — How Pre-Existing Conditions Affect Permanent Disability
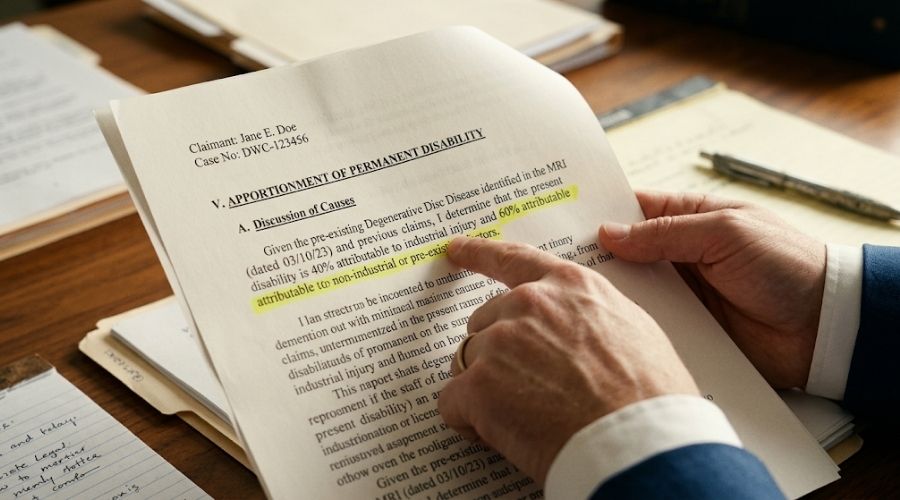
Apportionment is California’s mechanism for dividing permanent disability between the current work injury and pre-existing conditions, prior injuries, or non-industrial factors. Under Labor Code Section 4663, if a physician determines that a portion of your current permanent disability pre-existed the work injury or was caused by factors unrelated to employment, that portion is carved out of the employer’s responsibility. The employer pays only for the work-related share.
Apportionment is one of the most aggressively used and most heavily disputed tools in California permanent disability cases. An insurer whose physician apportions 40% of a 50% permanent disability rating to pre-existing causes reduces the insurer’s liability from a 50% claim to a 30% claim — a difference of tens of thousands of dollars in total benefit payments. Challenging apportionment requires medical evidence specifically addressing the current work injury’s independent contribution to the impairment — not just its co-existence with a prior condition. An attorney experienced in permanent disability disputes can identify when apportionment claims are factually unsupported and build the medical record needed to contest them effectively.
Side-by-Side Summary — Temporary vs. Permanent Disability in California
To put the key differences in one place: temporary disability begins when an injury prevents work and ends at MMI, the 104-week cap, or return to work — whichever comes first. Permanent disability begins at MMI when a lasting impairment remains and continues for a scheduled number of weeks based on the disability rating. Temporary disability is paid because you cannot earn; permanent disability is paid because of physical impairment regardless of whether you are currently earning. Temporary disability rates are adjusted annually by the SAWW; permanent partial disability weekly rates are set by statute and do not change annually. You cannot work while receiving TTD without triggering TPD or benefit termination; you can work while receiving PPD with no effect on entitlement. Temporary disability is tax-free; permanent disability is also tax-free. Settling before MMI risks undervaluing permanent disability; settling after MMI with a complete medical record produces the most accurate and defensible settlement value.
For more on how the full workers’ compensation claim process unfolds from injury to final resolution — including the settlement structures that determine whether future medical care stays open — see our complete guide on workers’ comp vs personal injury in California and our post on how long you have to report a work injury in California.
Frequently Asked Questions
What is the main difference between temporary and permanent disability in California workers’ comp?
Can I work while receiving permanent disability benefits in California?
What happens when temporary disability runs out before I am fully recovered?
How is a permanent disability rating determined in California?
What is apportionment and how does it affect permanent disability?
Not Sure Whether Your Disability Is Temporary or Permanent? Talk to an Attorney
The transition from temporary to permanent disability is the stage where most California workers’ compensation claims are won or lost financially. Oracle Law Firm | Accident & Injury Attorneys helps injured workers throughout Southern California navigate MMI determinations, permanent disability ratings, apportionment disputes, and the settlement structures that protect long-term medical coverage. No upfront fees, no obligation. Contact our team today before any settlement offer is accepted.